“Should I buy that truck before December 31 to save on taxes?” It’s one of the most common year-end questions business owners ask, and the honest answer is that it depends on the truck.
If the business needs it, or it will earn more than it costs, buying before year-end can be a smart move with a nice tax benefit attached. If the main reason is the deduction, you may be spending real cash to save a fraction of it. For government contractors heading into a year-end with funding uncertainty and estimated tax payments on the calendar, that tradeoff deserves a closer look.
This guide walks through the 2026 rules, the math behind a deduction, and a comparison that often surprises owners: what happens when the same dollars go into a retirement plan instead.
How much does a tax deduction actually save you?
A deduction lowers your taxable income. It doesn’t refund what you spent. The tax savings equal the deduction multiplied by your tax rate, and the rest of the money is still spent.
Here’s a hypothetical example using an assumed combined tax rate of 30 percent. Your actual rate depends on your entity, income, deductions, and state.
- Spend $50,000 on equipment.
- Tax saved: $50,000 × 30% = $15,000.
- Net cash cost: $50,000 minus $15,000 = $35,000.
If that equipment is going to help the business perform contracts, win work, or run more efficiently, the $35,000 is buying something valuable. If it’s going to sit in a corner, the business just spent $35,000 to avoid $15,000 of tax.
This picks up where last week’s article left off, on why you can owe taxes without the cash. Tax follows profit, and the bill has to be paid in cash, which is exactly why a December purchase deserves more than a gut-feel decision.
What changed for equipment deductions under the 2025 federal tax law?
The 2025 federal tax law (Public Law 119-21, commonly called the One Big Beautiful Bill) made year-end equipment purchases even more tempting. According to the IRS, it permanently restored 100 percent bonus depreciation for qualified property acquired after January 19, 2025. That means many equipment purchases can be deducted in full in the year they’re placed in service rather than spread over several years.
The law also raised the Section 179 expensing limits. For tax years beginning in 2026, the IRS sets the maximum Section 179 deduction at $2,560,000, and that limit begins to phase out once qualifying purchases placed in service during the year exceed $4,090,000 (IRS Rev. Proc. 2025-32).
Those rules are generous, and for businesses that need to invest, they’re valuable. They also make it easier to buy things for the wrong reason. A larger deduction doesn’t change the basic math above. You still spend the full amount to save a portion of it.
When does a year-end purchase make good business sense?
A year-end purchase usually makes sense when one of two things is true.
The first is need. If you can’t perform the contract, keep people safe, or meet a requirement without it, the purchase should happen anyway, and buying before December 31 may simply move the deduction into a year when it helps.
The second is return. If the equipment will help the business earn more than it costs, through new capacity, lower operating costs, or work you couldn’t take on before, the investment can pay for itself, with the deduction as a bonus.
Before you buy, ask two questions: does the business actually need it, and what does it do to your cash and your contract pricing, not just your tax bill?
If you’re still on the fence, add a third: will this equipment earn the business more than that same money would earn for you in your retirement account?
That third question matters because there is often another place for the money to go.
Is there a better way to lower taxes and keep the money?
For many owners, retirement contributions are the better year-end move. Contributions to a qualified retirement plan can reduce taxable income, just like a deduction for equipment. The difference is where the money ends up. Instead of leaving the business, it stays yours, invested for the future.
For 2026, the IRS sets the employee deferral limit for 401(k) plans at $24,500, and the overall limit on contributions to a defined contribution plan, including employer contributions, at $72,000 (IRS Notice 2025-67). How much you can contribute depends on the type of plan, your wages, and your business structure, so this is a conversation to have with your CPA before December 31.
One honest caveat: traditional retirement contributions are tax-deferred, not tax-free. You’ll pay tax when you take it out, but in the meantime it’s growing for you, not the IRS.
What do the three paths look like side by side?
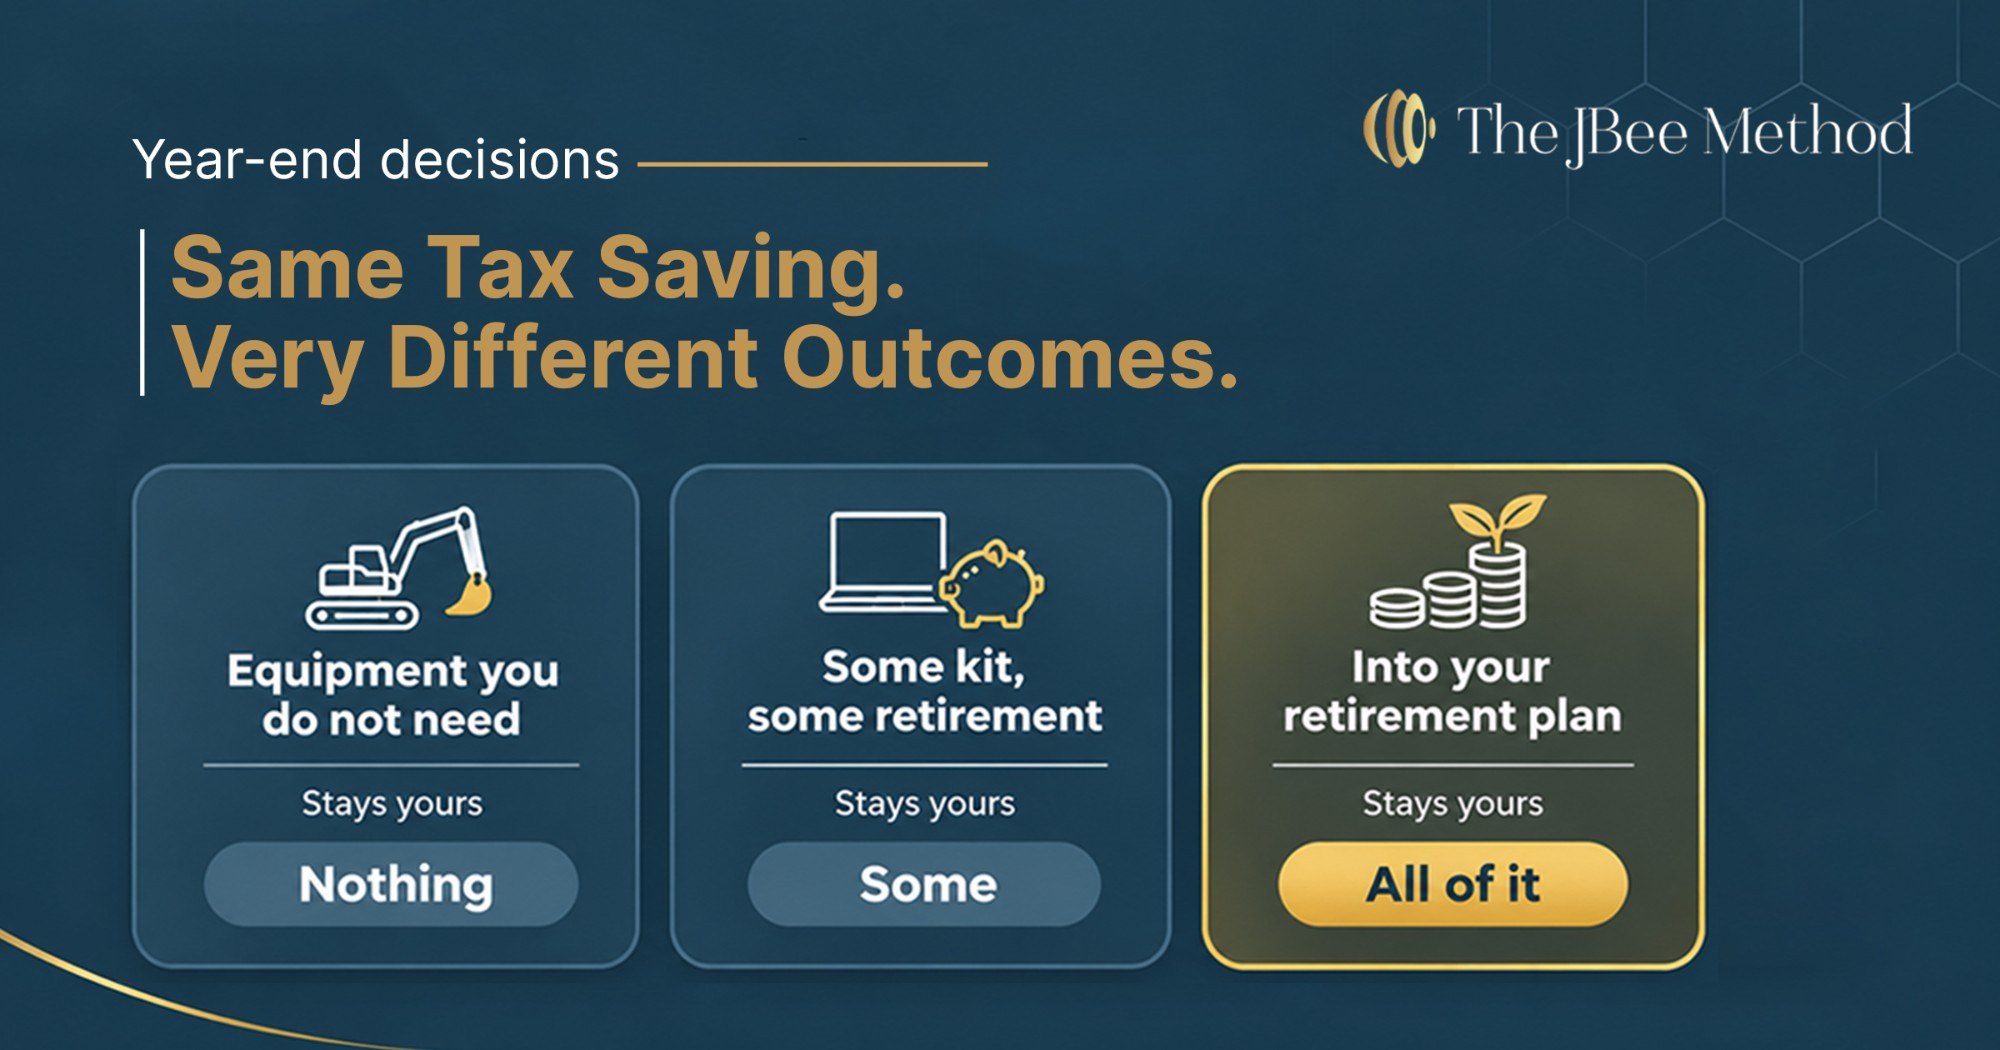
Here’s a hypothetical comparison. Each path produces the same $15,000 of tax savings at an assumed 30 percent rate, which requires $50,000 of deductions ($15,000 divided by 30% = $50,000). Growth assumes a hypothetical 7 percent annual return over 20 years, a growth factor of 1.07 to the 20th power, or about 3.8697. Returns are not guaranteed, and this is an illustration, not a projection.
Path A: Buy $50,000 of equipment the business doesn’t need.
- Tax saved: $15,000.
- Money that stays yours: $0.
- Net cash gone: $35,000.
Path B: Contribute $50,000 to retirement, for example a $24,500 employee deferral plus a $25,500 employer contribution, within the $72,000 limit and subject to plan and wage rules.
- Tax saved: $15,000.
- Money that stays yours: $50,000.
- Hypothetical value in 20 years: $50,000 × 3.8697 = $193,484.
Path C: Buy $20,000 of equipment the business actually needs and contribute $30,000 to retirement.
- Tax saved: $15,000.
- Money that stays yours: $30,000.
- Hypothetical value in 20 years: $30,000 × 3.8697 = $116,090.
The tax savings are identical. What changes is whether the money builds something for the business, for you, or for nobody.
What about cash?
There’s one more piece, and for government contractors it’s an important one. Money contributed to a retirement plan is generally set aside until retirement. Cash spent on equipment is gone too. Before you choose either path, make sure the business can still cover payroll, subcontractors, and upcoming tax payments. A 13-week cash forecast is the quickest way to see whether that room is really there.
That matters more than usual this year. Current federal funding runs through December 11, and the final 2026 estimated tax payment for individuals is due January 15, 2027. We’ll cover how to plan for those dates together next week.
Questions to ask before you spend to save
- Would I make this purchase if there were no tax benefit at all?
- Does the business actually need it, and what does it do to my cash and contract pricing?
- Will it earn the business more than that same money would earn in my retirement account?
- Have I talked with my CPA about which retirement options fit my business before December 31?
- After any year-end move, will I still have the cash for payroll and my January estimated payment?
Spending money just to get a deduction isn’t the smartest way to cut your taxes. When the business needs it or it earns a real return, buy it and enjoy the deduction. When it doesn’t, there are usually better ways to keep more of what you earned.
For the wider picture of how tax planning sits alongside cash flow and compliance, see our guide to cash flow, tax strategy, and financial compliance for government contractors.
This article is general information, not tax or investment advice for your specific situation.
Sources
- IRS, Working Families Tax Cuts, Businesses: irs.gov/newsroom/working-families-tax-cuts-businesses
- IRS, Rev. Proc. 2025-32 (2026 inflation adjustments): irs.gov/pub/irs-drop/rp-25-32.pdf
- IRS, 401(k) limit increases to $24,500 for 2026 (IR-2025-111): irs.gov/newsroom/401k-limit-increases-to-24500-for-2026
- IRS, Notice 2025-67: irs.gov/pub/irs-drop/n-25-67.pdf
Know your numbers cold
Start with the free cash flow training, then book a GovCon financial readiness call.