It’s one of the most frustrating conversations a business owner can have with their accountant. The year went well. Revenue grew. Maybe you won new work or expanded an existing contract. Then the tax estimate comes in, and the number doesn’t match how the bank account feels at all.
Year-end tax planning for government contractors starts with understanding why that happens. The short version is that your tax bill is based on profit, and profit and cash are two different numbers. The longer version is worth walking through, because once you see how the gap forms, you can plan for it while there is still time to do something about it.
Why do I owe so much tax when I don’t have the cash?
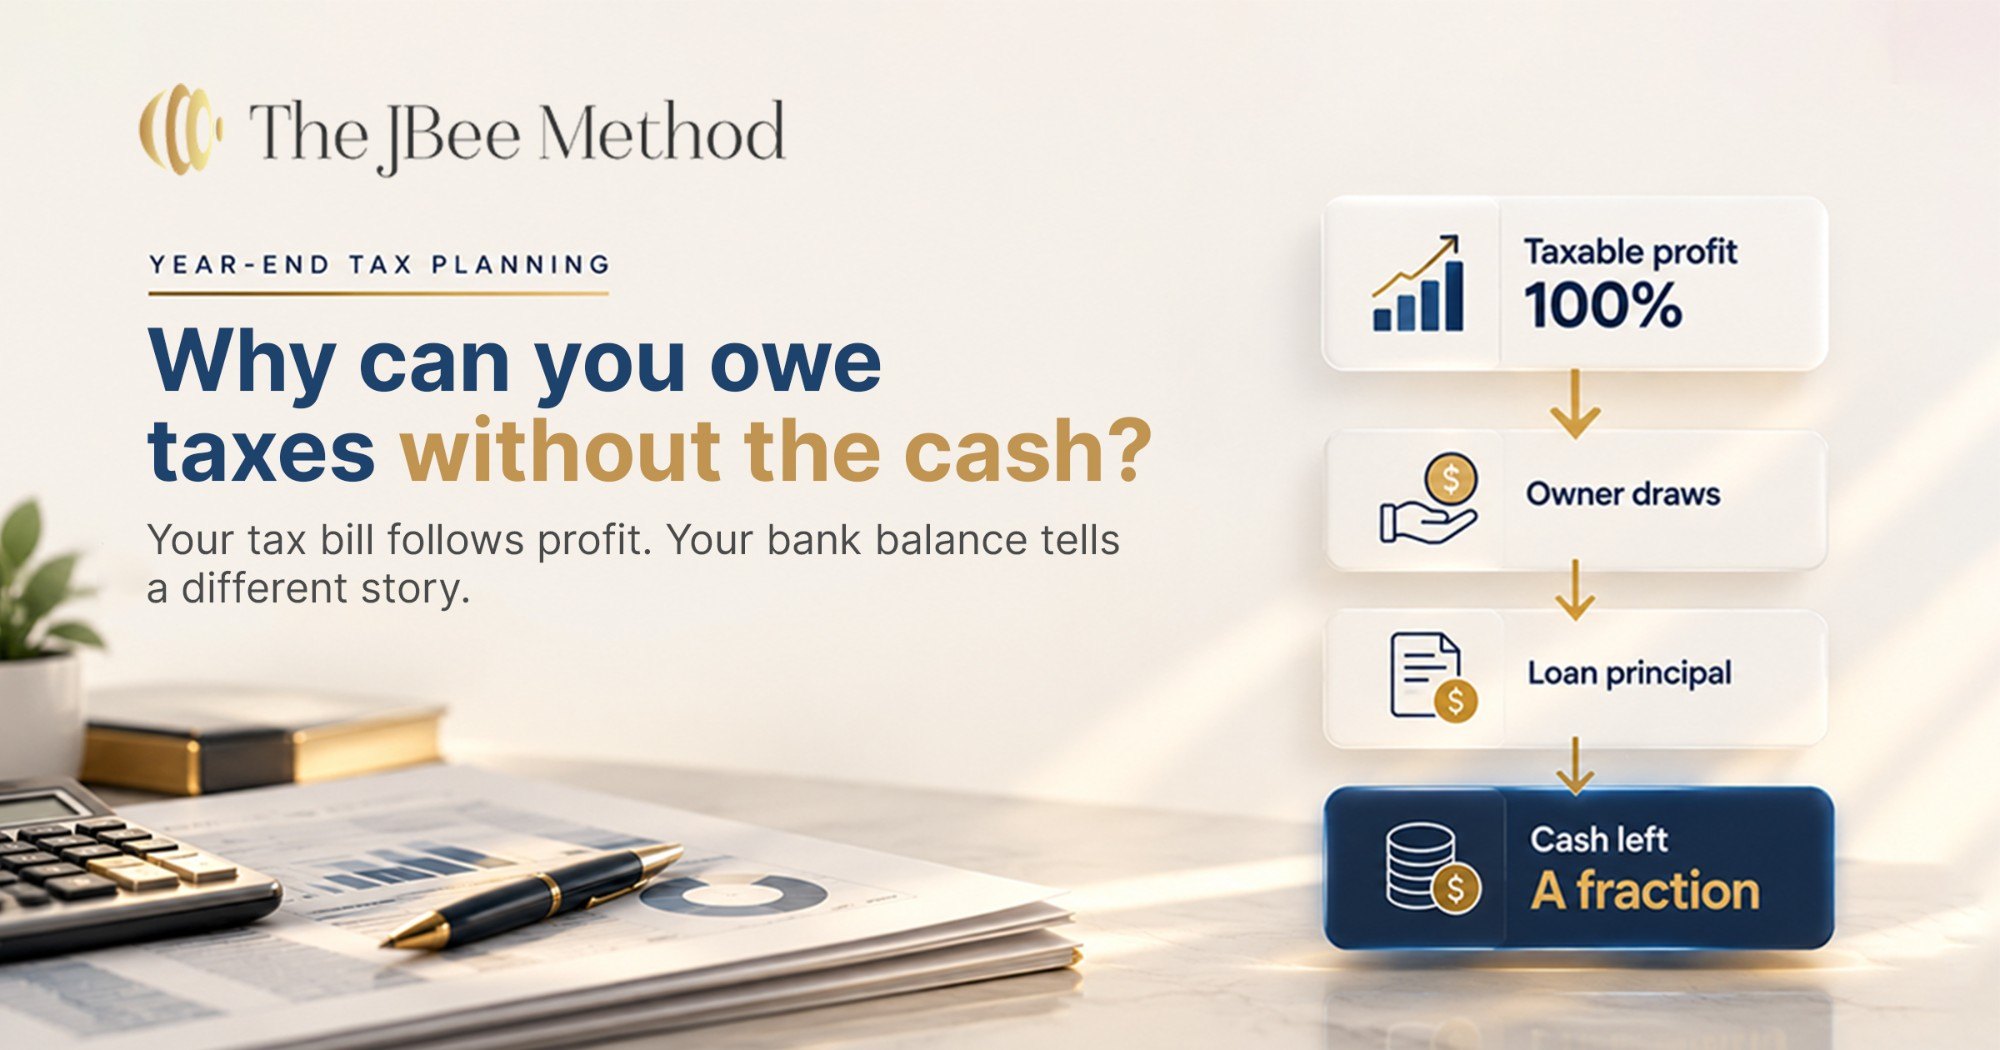
Your business income tax is calculated on taxable profit: what the business earned, minus the deductible expenses it paid to earn it. Your bank balance tells a different story. It reflects every dollar that came in and every dollar that went out, including plenty of things that never show up as a deduction.
Owner draws are a common example. If you took money out of the business to live on during the year, that cash is gone, but for most owners it didn’t reduce taxable profit. Loan principal is another. When you pay down a line of credit or an equipment loan, the interest may be deductible, but the principal generally is not. The cash leaves the bank, and the profit stays right where it was.
For businesses that report on the accrual method, there’s a third piece. Income can be counted when it’s billed rather than when it’s collected, so an invoice that hasn’t been paid yet can still be part of this year’s profit.
None of this means something went wrong. It means the bank balance and the tax return are answering different questions.
Is profit the same as cash flow?
No, and this is where a lot of tax surprises start. Profit tells you whether the business made money over a period of time. Cash flow tells you whether the money is actually available when you need it.
A business can be profitable and short on cash at the same time. It happens when profit has been spent on things that aren’t deductible, pulled out by the owner, or tied up in work that hasn’t been paid for yet. It also happens when growth moves faster than collections.
The tax bill doesn’t care which of those situations you’re in. It’s calculated on profit, and it has to be paid in cash.
Why government contractors feel the gap more in a growth year
Government contracting adds its own timing pressure. Contractors often cover payroll, subcontractors, insurance, travel, and materials before payment for that work arrives. Depending on the contract, there can be time between performing the work, invoicing, acceptance, and payment. Subcontractors may wait longer, since their timing often depends on when the prime gets paid.
In a steady year, that timing is usually manageable. In a growth year, it stretches. Every new contract or added scope means more cash going out ahead of more cash coming in. The business may be more profitable than it has ever been and still feel tighter than it did last year. It is the same squeeze behind the post-award cash flow gap, arriving this time with a tax bill attached.
That’s exactly the kind of year when tax planning matters most, because the profit is real even when the breathing room isn’t.
How are business owners taxed on profit they never took out?
If your business is an S corporation, a partnership, an LLC taxed as either one, or a sole proprietorship, the profit generally passes through to the owners’ personal tax returns. Owners are taxed on their share of the business profit whether or not that money was distributed to them.
So if you left profit in the business to fund the next contract, hire ahead of a new award, or keep a cushion for payroll, you’ll still owe tax on it. That’s often the moment owners realize the tax bill and the cash plan were never connected.
The 2025 federal tax law (Public Law 119-21, commonly called the One Big Beautiful Bill) made the 20 percent qualified business income deduction permanent, which can reduce the tax on pass-through profit for eligible owners. That helps, but it doesn’t change the basic math. Tax follows profit, and you need cash to pay it.
What does the profit and cash gap look like in real numbers?
Here’s a hypothetical example to show how quickly the gap forms. The numbers are for illustration only.
A contractor finishes the year with $400,000 of taxable profit. During the year, the owner took $150,000 in draws to live on and paid $80,000 of principal on a line of credit.
- Cash left from that profit: $400,000 minus $150,000 minus $80,000 = $170,000.
- Now assume, for illustration, a combined tax rate of 30 percent on that profit. Estimated tax: $400,000 × 30% = $120,000.
- What’s left after the tax bill: $170,000 minus $120,000 = $50,000.
On paper, this owner had a $400,000 year. In practice, they have $50,000 of cushion to carry payroll, subcontractors, and the next contract into January. If a few payments run late, that cushion can disappear quickly.
The 30 percent rate is an assumption for this example, not a typical or recommended rate. Your actual rate depends on your entity, income, deductions, and state.
Should I spend money before December 31 to lower my tax bill?
Maybe, but only if the spending makes sense on its own. A deduction reduces tax by a fraction of what you spend. Using the same 30 percent illustration, spending $10,000 saves about $3,000 in tax and still costs $7,000 in cash ($10,000 minus $3,000).
If the business needed that purchase anyway, the timing can be smart. If it didn’t, you’ve traded a tax problem for a cash problem. There are often better options, including some that let you keep the money. That’s what we’ll cover next week.
What should year-end tax planning for government contractors cover before December 31?
The value of planning in November is that you still have choices. In April, you mostly have a bill.
A useful year-end review usually covers five things:
- Year-to-date profit, not just the bank balance. That requires current, reconciled books.
- A projected tax bill for the year. Even a rough estimate tells you how much cash to protect.
- Where that cash will come from, whether that’s operating cash, a reserve, or a change in owner draws for the rest of the year. A 13-week cash forecast is the quickest way to see it.
- Year-end decisions that change the picture. Some spending and timing decisions reduce taxes. Others only reduce cash.
- A conversation with your CPA before December 31, not after.
How do estimated tax payments fit in?
Owners who expect to owe tax generally pay it during the year through estimated payments. According to the IRS, individuals, including sole proprietors, partners, and S corporation shareholders, generally have to make estimated tax payments if they expect to owe $1,000 or more when they file.
If your business grew this year, payments based on last year’s numbers may not have kept pace. The IRS explains that most taxpayers avoid the underpayment penalty if they paid at least 90 percent of the current year’s tax or 100 percent of the prior year’s tax, whichever is smaller, with special rules for higher-income taxpayers. Your CPA can tell you which rule applies to you.
The final 2026 estimated payment for individuals is due January 15, 2027. We’ll come back to that date, and how it lines up with other year-end pressure points, later this month.
Questions to ask yourself this month
Before the year closes, take a few minutes with these:
- Do I know my year-to-date profit, or only my bank balance?
- What will my 2026 tax bill likely be, and where is that cash coming from?
- Have my estimated payments kept up with this year’s growth?
- What decisions can I still make before December 31?
If you can answer all four with confidence, you’re in a good position. If some of them make you pause, that’s useful information, and November is a much better time to find it than April.
For the wider picture of how tax planning sits alongside cash flow and compliance, see our guide to cash flow, tax strategy, and financial compliance for government contractors.
This article is general information, not tax advice for your specific situation.
Sources
- IRS, Estimated taxes: irs.gov/businesses/small-businesses-self-employed/estimated-taxes
- IRS, Working Families Tax Cuts (Public Law 119-21 provisions): irs.gov/newsroom/working-families-tax-cuts
- IRS, Taxpayer Advocate Service, important tax dates for 2026.
Know your numbers cold
Start with the free cash flow training, then book a GovCon financial readiness call.